Keep the roof clear and document its age
Clear leaves, needles, and debris from the roof and gutters before an inspection. Keep permit, invoice, or warranty records for roof work—carriers often focus on roof age and visible condition.
Personal · Professional · Proven
Jeremy Carter · Matt Menke
Home and auto insurance for Carmel-by-the-Sea, Pebble Beach, Pacific Grove, Monterey, and all of California.
Hard-to-place Peninsula homes welcome — FAIR Plan, DIC, earthquake, flood, and non-renewal rescue.
Jeremy Carter·(831) 204-0393·[email protected]·@jeremycarteragency
Matt Menke·(831) 224-2141·[email protected]·@mattInsuresCA
Carmel-by-the-Sea | Jeremy Carter CA Lic. #4187910 | M. Menke CA Lic. #4476998
Latest from @mattInsuresCA · Oct 5 CA FAIR Plan rates change Oct 15. Statewide avg 29.1% — high-risk Peninsula homes often feel more. FAIR Plan is fire only (not water, theft, or liability). Ask about a DIC companion. Check your renewal date.What We Cover
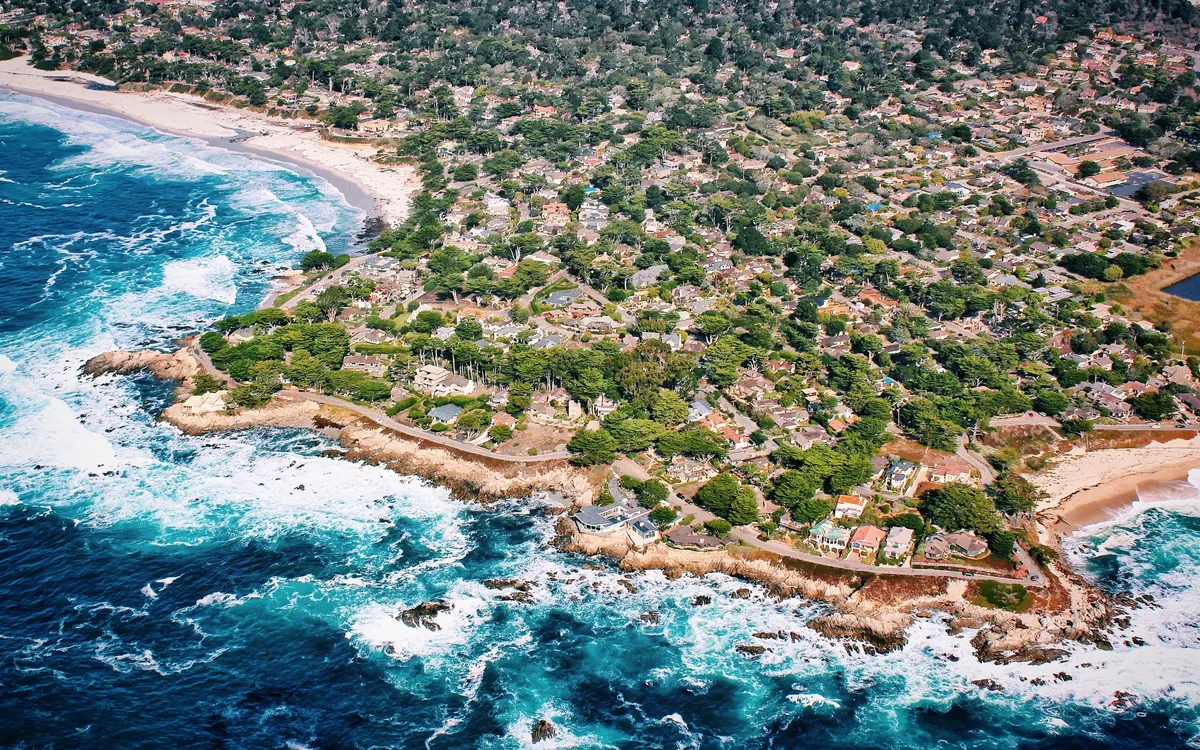
Your home is your biggest investment. Protect the structure, what’s inside it, and your liability — from primary residences to coastal second homes.
Coverage that fits how you actually drive — from daily commuters to the weekend garage queen — with options worth comparing.
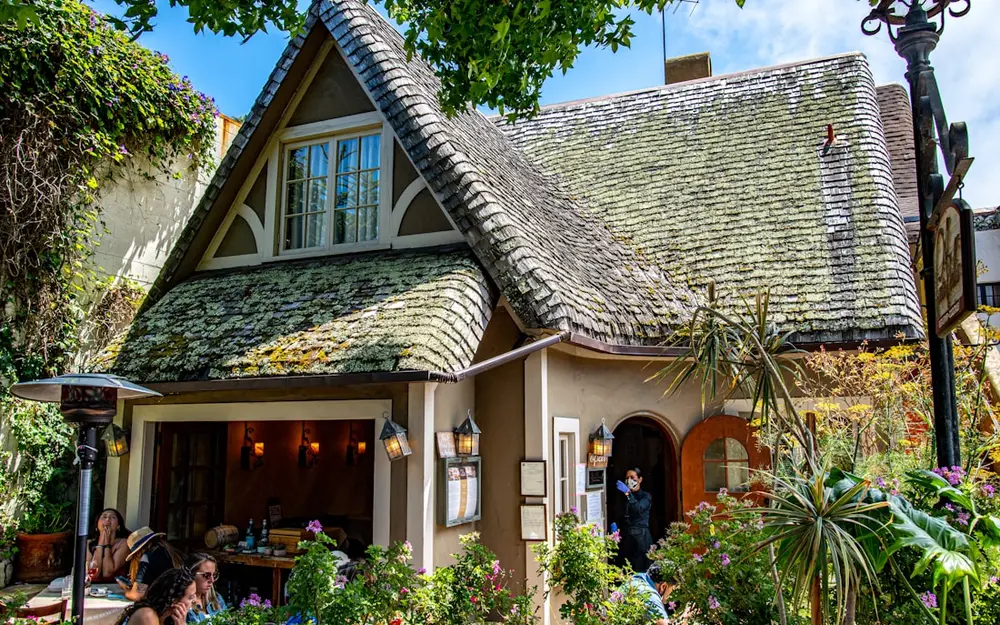
From the first LLC to a growing fleet, keep your business protected so one bad day never becomes a bad year.
Meet the Team
When you call, you get us — not a call center.
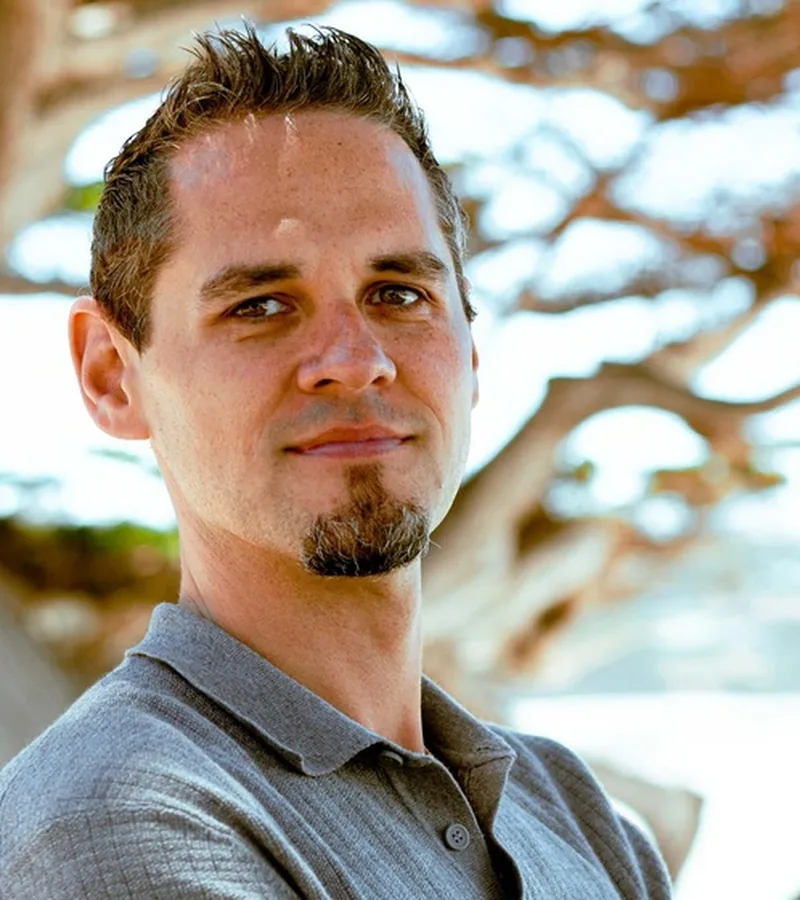
Jeremy Carter is the agent and owner behind The Jeremy Carter Insurance Agency. For over a decade, he has helped individuals, families, and business owners protect what matters most — with an approach that is personal, discreet, and built on lasting relationships. The agency was founded on a simple standard: the kind of attentive, white-glove service clients deserve, from a team that treats every policy like its own.
From first homes to complex commercial risks — restaurants, contractors, auto shops, inns, and short-term rentals — Jeremy leads every client relationship with the same goal: strong coverage at a competitive premium the market will offer, explained clearly and serviced for the long haul.
Matt Menke has spent his whole career earning the Monterey Peninsula’s trust — first in its driveways, now in its living rooms. He came up in the family business, Larry Menke Inc., and went on to more than sixteen years serving clients at Jaguar Land Rover Monterey and the Sam Linder Auto Group. Two decades taking care of people and what they drive taught him one thing above all: in a community this tight, your reputation comes down to whether you pick up the phone and tell people the truth.
As a licensed producer with The Jeremy Carter Insurance Agency, Matt helps families and small businesses from Carmel and Pacific Grove to Pebble Beach and Monterey protect what matters — home, auto, umbrella, and business coverage — with plain-English reviews, honest answers, and real quotes compared side by side. No jargon, no fear-selling, no radio silence at renewal.
How It Works
Send the quote form or call. Tell us what you need covered — it takes about five minutes.
We shop your coverage, then walk you through the options side by side — in plain English, with no pressure.
Pick the fit, sign, and we bind the coverage you choose. We handle the paperwork and stay your point of contact for life.
Already a Client?
Accident, storm, break-in — call us first. We’ll walk you through your carrier’s claim process and stay on it until it’s resolved.
Call (831) 224-2141New car, new driver, moving, refinancing? Email the details and we’ll update your policy and confirm the change in writing.
Request a ChangeNeed a certificate of insurance for a job, or proof of coverage for a lender or the DMV? Usually turned around the same business day.
Request DocumentsRates and life both change. A free yearly review makes sure you’re not overpaying — or underinsured — as things evolve.
Schedule a ReviewInspection Ready
A few practical checks that help Monterey Peninsula homes show well on insurer inspections and reduce common claim-related surprises. Requirements vary by carrier—ask us before you schedule work.
Clear leaves, needles, and debris from the roof and gutters before an inspection. Keep permit, invoice, or warranty records for roof work—carriers often focus on roof age and visible condition.
Older panels and outdated wiring (such as certain recalled brands, fuse boxes, or knob-and-tube) are common underwriting flags. If you’ve upgraded the panel or wiring, have the permit or electrician invoice handy.
Visible leaks, outdated supply materials (for example polybutylene or aging galvanized lines), and water damage are frequent inspection notes. Fix active leaks promptly and keep repair photos and invoices.
Keep the first few feet around walls, decks, and stairs free of mulch, firewood, dry debris, and combustible clutter. CAL FIRE and IBHS home-hardening guidance emphasize ember control at the structure edge.
Attic, eave, and foundation vents that allow embers in are a frequent wildfire concern. Ember- and flame-resistant vents (or fine noncombustible mesh per CAL FIRE guidance) and enclosed eaves appear in FAIR Plan structure-hardening themes—confirm products and local code with a licensed contractor.
California requires smoke alarms in bedrooms and outside sleeping areas on each level, and carbon monoxide alarms where fuel-burning appliances, fireplaces, or attached garages are present. Replace batteries on a schedule and note locations for the inspector.
California seismic bracing typically calls for proper strapping (often two straps for standard tanks). Garage gas units may also need elevation off the floor—local building rules apply.
Many carriers look for a permanent pool barrier with a self-latching or locked gate, and some exclude or limit trampoline, diving-board, or slide liability. Disclose these features up front so the policy matches the property.
Breed, bite history, and how dogs are secured can affect liability underwriting. Accurate application answers help avoid later coverage disputes after an incident.
“Vacant” and “unoccupied” are treated differently by many carriers and may need a different policy form. Seasonal homes, remodels, and homes between owners should be disclosed before binding or renewal.
Tips are educational; carrier and local rules vary. · M. Menke CA Lic. #4476998
Client Words
Matt was incredibly responsive, helpful, and easy to work with. He was always available when I had questions and was very quick to help me find the best insurance option for my home. I really appreciated his professionalism, attention to detail, and willingness to go the extra mile. Highly recommend Matt!— Alessia Ucelli on Matt
Matt was extremely helpful and very professional. My new insurance resulted in a significant decrease in my homeowners insurance premium.— Barby Barone on Matt
Matt is very helpful and knowledgeable — helping me acquire the proper insurance policy and continues to be helpful, after the fact, when questions come up.— Karen Colson on Matt
“Jeremy is very responsive and delivers results! My old policy wasn't being renewed, and my prior insurer provided me with an outrageous quote days before my policy's expiration! Jeremy was able to turn things around in record time to avoid me having a lapse in insurance with a competitive policy. I highly recommend Jeremy in his flexibility, responsiveness and professionalism. I plan on moving other insurance policies over.”— Ken R
“I've worked with a lot of insurance agents over the last few decades and none have been as detailed, thoughtful and had as much integrity as Jeremy. He's showed up for my family again and again, going above and beyond, every.single. time. He offers the best policies and is wonderful to work with.”— Debra G
“The Readers Digest version is that I contacted Jeremy when I discovered my dad's long time insurance broker was no longer going to cover condos in California. I had about 20 hours to find a new broker. Jeremy solved my problem and covered my dad's condo in less than 2 hours. From the moment I placed my first call to the time we had a new policy, it was less than 2 hours. I went from slightly panicked to incredibly grateful.”— Kathy A
“I have worked with Jeremy on many real estate transactions to help our clients find the best possible insurance for their needs, (as well as my own)! Jeremy is quick to respond, understands contractual timelines with a sense of urgency, is thorough in his research, and is a great communicator. I am so grateful to have him on my team of go-to professionals.”— Claudia McCotter
“Jeremy is the only insurance agent in the Monterey Peninsula area that could offer me a homeowners policy. He goes above and beyond to give great service and is delightful to work with. Definitely recommend!”— Robin Cauchois
“Jeremy is the person to see!! He is a very reliable and honest agent who has the ability to offer customizable insurance solutions to address every clients needs!! He offers all policies and I highly recommend his services!!”— Violette Olinger
“Best insurance agent out there! Personable, reliable and prompt. When I had my accident, he answered right away, answered my questions and concerns and took care of everything. He truly cares for all of his customers and will go above and beyond.”— Natasha Monsauret
“Jeremy has been so helpful and accommodating. I have recommended him to several friends, its great to have an agent that will always help and be available.”— Cynde E
“Jeremy is great to work with. He's very responsive and quick to answer our questions.”— Tracy B
“Jeremy was responsive and efficient in arranging our insurance”— Fiona P
From Google reviews for The Jeremy Carter Insurance Agency · ★★★★★ only · Individual experiences; savings and results vary and are not guaranteed. · See us on Google
Worked with us? Share your experience
Peninsula Coverage Note
162 homes in Pebble Beach (93953) are on the CA FAIR Plan — four times the 2021 count, per the FAIR Plan’s own zip data.
FAIR Plan covers fire (and related perils), not water damage, theft, or liability. If you’re on it — or staring at a non-renewal — a Difference in Conditions (DIC) companion policy can fill those everyday gaps while we shop the admitted market.
Some DIC or specialty placements may use non-admitted (surplus lines) markets. Those carriers are not members of the California Insurance Guarantee Association (CIGA); we provide the required disclosure when you apply.
The FAIR Plan asked for a 35.8% rate increase; the state approved 29.1%, effective mid-October on new and renewal dwelling policies. Most of that lands on the wildfire portion of the premium, so high-risk Peninsula homes feel more than 29%. Check your renewal date before it hits.
Talk through your optionsQuestions
No. Quotes from The Jeremy Carter Insurance Agency are always free and carry no obligation. We compare options across multiple carriers; you decide if one fits.
Some carriers order consumer reports when quoting. In California, credit scores are not used to rate auto insurance; for other lines, practices vary by carrier and are typically soft inquiries that don't affect your score.
For a home quote: the property address and basics like year built, roof age, and square footage. For auto: your driver’s license and vehicle info (year/make/model or VIN). Either way, your current policy helps if you have one — five minutes on the phone usually covers it.
Yes — that’s the point of working with one local team. Auto, home, and business coverage under one relationship, and bundling discounts may be available.
Call The Jeremy Carter Insurance Agency first at (831) 224-2141 or (831) 204-0393. We review your policy with you, help you file with the carrier, and stay in touch with you and the carrier throughout the claim. Coverage decisions are made by the insurance company.
The California FAIR Plan typically covers fire and related perils only — not water damage, theft, or liability. A Difference in Conditions (DIC) companion policy can help fill many of those gaps, subject to its terms and availability. The Jeremy Carter Insurance Agency in Carmel helps Peninsula homeowners combine FAIR Plan + DIC or shop back into the admitted market after a non-renewal. Some DIC or specialty placements may use non-admitted markets; required disclosures are provided at application.
Know someone overpaying for insurance? Send them our way — the best compliment a client can give.
On X
Rate trends, coverage tips, and Peninsula news — follow along at @mattInsuresCA.
CA FAIR Plan rates change Oct 15. Statewide avg 29.1%. High-risk Peninsula homes often feel more — most of it is wildfire premium. FAIR Plan is fire only (not water, theft, or liability). Ask about a DIC companion. Check your renewal date.
The FAIR Plan asked for 35.8%. The state approved 29.1%, effective October 15 on new and renewal dwelling policies. Most of it lands on the wildfire portion of the premium, so high-risk homes see more than 29%. Check your renewal date before it hits.
Smoke can ruin a house the fire never touched. Soot is acidic and keeps eating drywall, ducts, and fabric for months. Smoke is a covered peril on a standard homeowners policy. Coming home to a smoke smell? Photograph it and open a claim before you clean.
Get Started
Tell us a little about what you need. You’ll get a personal response — usually the same business day.
Thanks — we’ll get back to you, usually the same business day. If nothing arrives, use the email fallback on the form.